<img height="1" width="1" style="display:none" src="https://www.facebook.com/tr?id=1642510189396513&amp;ev=PageView&amp;noscript=1">

Plan for the Worst. Live for the Best. In That Order

Some retirement advice makes you pick between protecting your money and enjoying it. After 25 years of doing this, we don’t believe in that choice. Plan for the worst first: price every fear, have a strategy to help cover every bill that has to happen, and do it thoroughly. Once the worst is planned for, it stops getting a vote, and you can spend the good years living on what you saved.

Retirement Is Changing

There Are Two Ways to Fail at Retirement

Everyone knows the first one: spend too much and run out. Much of the industry is organized around preventing it, and so is the math you do at three in the morning.

The second way gets less attention. You save your whole life, retire, and don’t feel safe enough to use any of it. The cruise stays a brochure in a drawer. The kitchen never gets redone. Researchers who followed retirees for almost two decades found the typical household still had about 80% of its savings nearly twenty years in. Among people who saved seriously, this failure is the common one.

We’ve been helping clients prepare for both since 2001. Twenty-five years of clients have shown us that protecting the money and enjoying it aren’t competing goals. Done in the right order, the protecting is what help makes the enjoying possible.
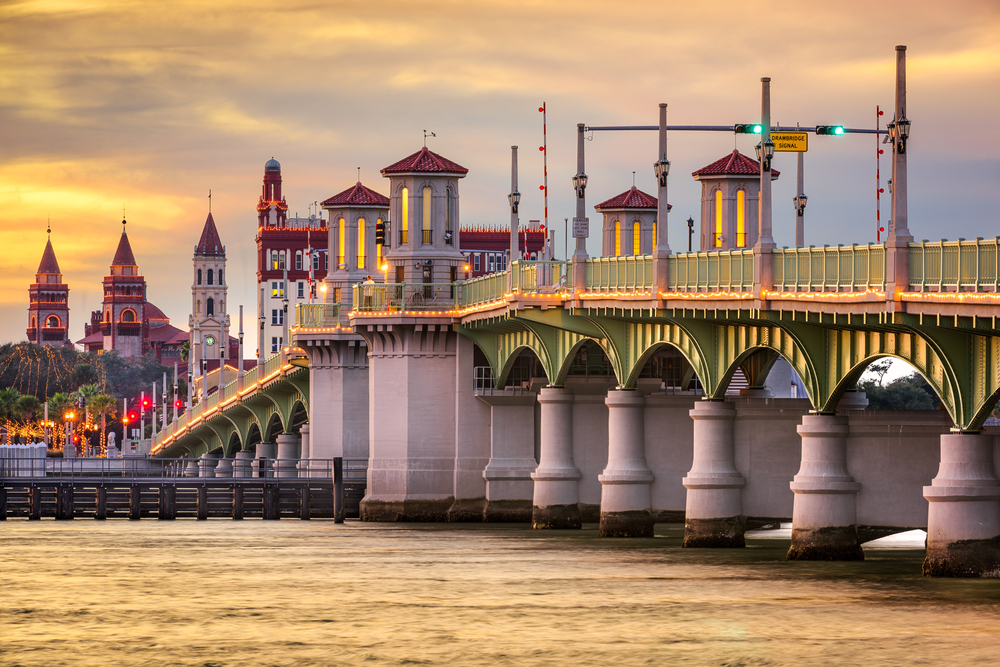
 

St. Augustine, Florida, USA city skyline and Bridge of Lions.

Everything We Do, in One Plan

We have access to a whole world of financial products at Stratton & Company: stocks and ETFs, bonds, brokerage CDs, and income products like annuities. Twenty-five years in this business has convinced us there’s no magic product out there, and no evil one either. We’ve seen every tool on that shelf used well and used badly. What matters is the plan, so we don’t recommend anything until your plan tells us what job needs doing. Every S&Co. client gets a complete strategy designed to help provide:


  • Dependable monthly income. Your essential bills, covered by money that shows up whether the market is up or down: Social Security claimed at the right time, pension options chosen with the surviving spouse in mind, and income products where a gap still needs filling.


  • Investment management. Once the bills are covered by dependable income, your portfolio can do what long-term money is supposed to do. We manage it for growth potential at a risk level that fits you, keep it diversified, and rebalance on a schedule. And because you’re not selling shares to buy groceries, a down year becomes something the portfolio sits through and has the potential to recover from.


  • A real cash reserve. The roof, the car, the health year that costs more than it should. We price those honestly and keep money for them in plain, boring accounts, so a surprise doesn’t force you to sell an investment at a bad time.


  • Money for the good stuff. Travel, projects, family, giving. Each gets its own account, funded monthly, so the fun is paid for before you go. People take trips they’ve already paid for.


  • Tax and distribution planning. Which accounts to draw from and when. Roth conversions in the years your tax rate is unusually low where appropriate. Required minimum distributions handled on purpose instead of in a scramble. Retirement is often one of the best tax-planning windows of many people’s lives, and many people let it close unused.


  • Estate coordination. We work with established local estate attorneys and CPAs on the legal side: beneficiaries checked and current, the survivor’s income planned in advance, and paperwork your family could pick up and understand without a translator.


How We Get Started

How We Get Started: We Price Your Life

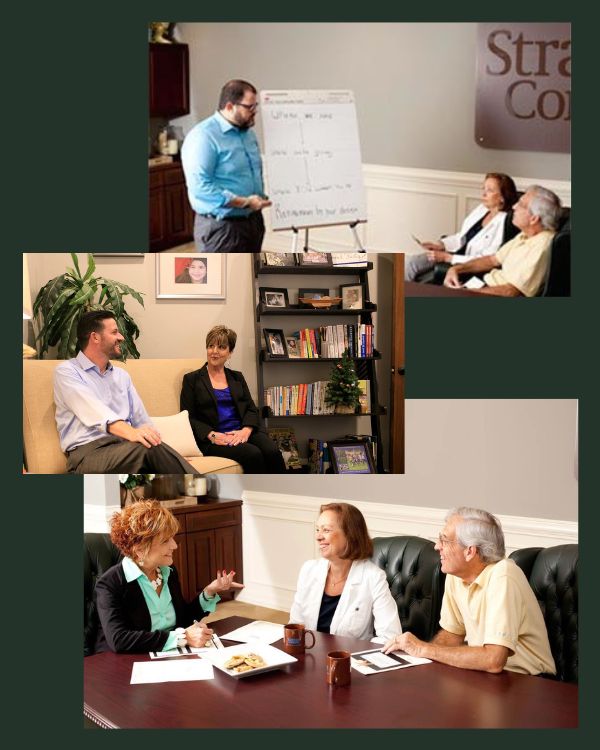
The most important meeting we run has no products in it and no projections. It has one rule, and we say it out loud at the start: let’s just assume all the bad stuff happens. Then we write your worries down, one at a time, and put a price on each. The market drop. The health scare. The roof. The long illness nobody wants to talk about.

That sounds like a depressing afternoon. It isn’t. People walk in carrying one big vague dread and walk out holding a short list of numbers, and numbers can be planned for. There’s no cost for any of this, no obligation, and you set the pace. If we turn out not to be a fit, the plan is still yours to keep and use anywhere you like.


Untitled design-12

HOW DOES OUR FINANCIAL CLARITY PROCESS BEGIN?

It Starts With Three Questions

What has to happen?

What does a month of being you actually cost? House, insurance, groceries, cars, the phone your grandkids tease you about. We get to the honest number, without the padding people build in when they’re nervous. Then we add up what already arrives on its own: Social Security, pensions, rental income. In our experience, the distance between those two numbers is usually a lot smaller than people fear.


What might happen?

The bad health year. A long illness. The surprise repairs, and the month one of you would someday face alone. Each one gets named, priced, and given its own money. The world doesn’t get any safer in that meeting, but your month becomes a known quantity, and known is plannable.


What could happen?

This is the good part. We aim to help you enjoy trips, projects, generosity, a Christmas that looks like Christmas. We price the dreams too, and set up accounts to help pay for them a little at a time. It can change what people let themselves want.

Add it all up, subtract what already shows up on its own, and you’re left with one number: what your savings needs to produce every month for the rest of your life. That’s the number we build the whole plan around, income and investments both.

Once Your Plan is Complete: Deciding to Become a Client

We keep adjusting the numbers with you until you’re happy with it. If you don’t want to go further, that’s the end of it and there’s no bill. If you do, the work still costs nothing. We’re paid through the investments we manage and the products that end up in your plan, and we’ll show you those numbers plainly before anything gets signed.

One more thing, because it often surprises people: sometimes we’ll tell you that you don’t need us. If your Social Security and pension already cover your bills, your income floor is already built, and we’ll say so. That conversation has happened plenty of times in 25 years, and we’d rather send you off with a handshake than with a product that had no job to do.

Get in Touch
Screenshot 2022-12-09 at 8.05.58 AM

“Plan for the worst. Live for the best. In that order.”

The First Document Is a First Draft

Be wary of any advisor who disappears once the paperwork clears. Retirement runs for decades, and a first-year plan rarely survives them unchanged. We actually tell clients on day one that the first version of a plan is usually about 75% right. Life moves, and people rarely admit the full size of their dreams in a first meeting.

So the reviews are where the real work happens. At least once a year we sit down together, re-check what your life costs, aim to top up the accounts that pay for next year’s plans, rebalance the portfolio, and make that year’s tax moves, including any Roth conversion the numbers make room for. It’s usually one meeting.

Also: no phone trees. A person answers. And yes, the monthly client events really are as fun as everyone says.

We keep the whole system simple on purpose, so it can still run smoothly when you’re 87 and is designed to not fall apart if your spouse someday had to take it over alone. If that sounds like your kind of firm, call us. There’s no cost and no obligation.

On a Personal Note

A few more things about S&Co.

forget_cookies_img
Don't forget your cookies!

We bake fresh chocolate chip cookies for every client who comes to the office! Careful, they are hard to put down!

event-client3
More than just office meetings!

We see all clients at annual reviews, but we also host regular dinners, trivia, outings, and other fun ideas that Grace, our event coordinator, cooks up!

children_hospital
We love Wolfson Children's Hospital

Ever since the Stratton family was helped so much through a difficult time with a child, we have tried to give back with regular toy drives to Wolfson.